Tech’s Bear Market Roster
Source: The Kobeissi Letter
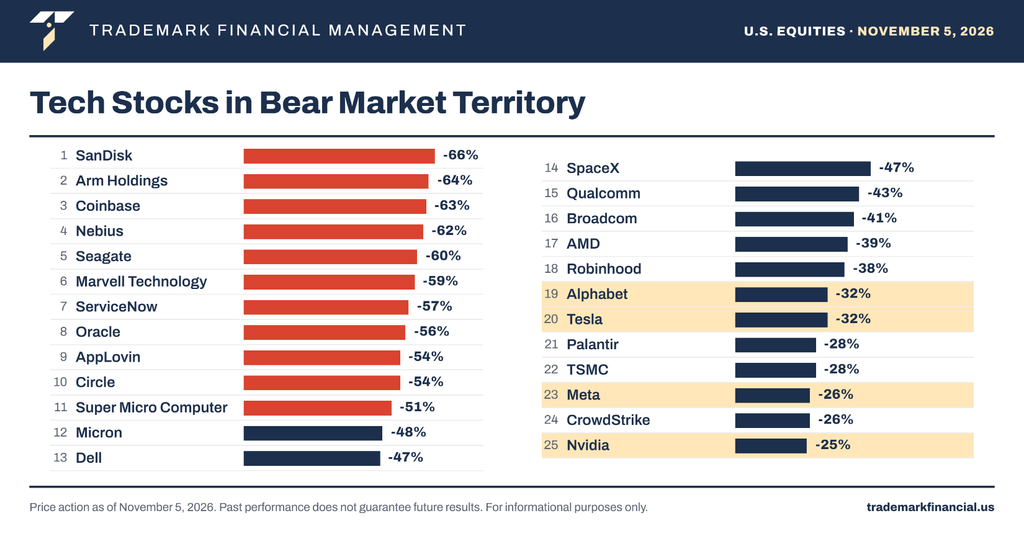
As of writing this, it is November 5th, 3:00PM on the dot and the S&P 500 closed at roughly 7,350, a drop in price of 4.36%. Other notable closings of the day: Semiconductors (SMH) -11.46%, technology (XLK) –8.22%, memory (DRAM) -17.11%, and broad artificial intelligence (BAI) –12.74%. Technology and the broad AI trade just experienced a day of extreme loss where the index saw a wipeout of over $2T in market cap by midmorning. This heavy sell-off in AI, semiconductors, data center infrastructure, and many more was following a Democratic sweep in the Senate and House of Representatives with investors now gaining a sense of concern regarding how the political shifts will constrain and slow down the AI buildout. This was a complete flush out, a de-risking and valuation reset of these high-flying stocks that were already on the cusp of vulnerability as of late, but maybe this is not necessarily a bad thing. No other technology in history has moved this quickly from a progression and adoption standpoint, but I do not believe the same can be said for the security and deliberate regulations that are needed to ensure the world can move forward with this technology safely. After yesterday’s strong day that was guided by defensive hedges closing and capital being deployed, the uncertainty that focused on midterms transitioned to what the future of the AI buildout will look like under Democratic power. Sentiment always changes and focuses on an area, both positively and negatively, but one thing that never changes is the significance that it plays in driving price action in the marketplace. It seems that very few parts of the market were able to escape this selloff, but if there was a positive for the day, I would highlight that bonds ended the day up with Bloomberg Agg finishing +0.22% and mitigating some portfolio losses.
The S&P 500 Hits Extreme Oversold Territory
Source: Bespoke Investment Group
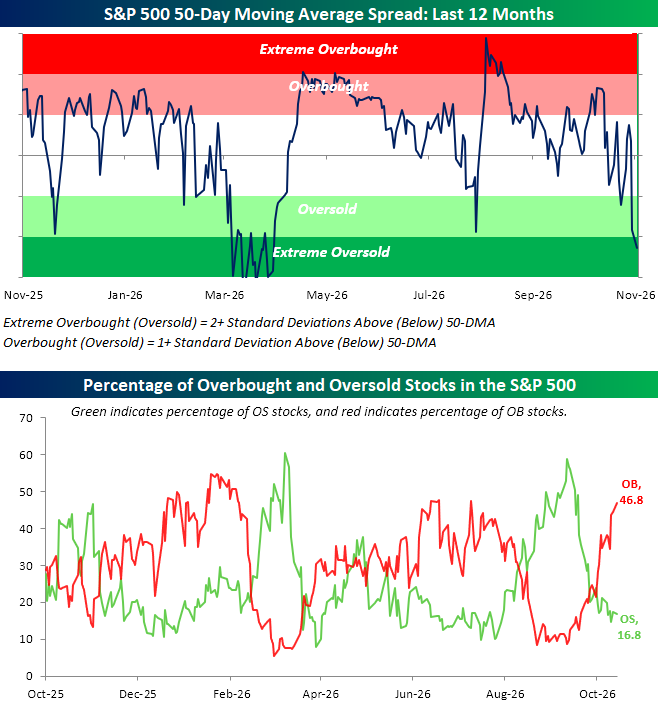
Before today’s collapse, 9 out of the 11 official market sectors had at least 70% of its constituents trading above their 20-day moving average, minus energy and technology. What makes that interesting is the very top chart of the two where the S&P 500 is currently sitting at extreme oversold levels, but the near-term breadth of the market has been trending upwards. Taking it a step further, the bottom chart of the two tells us that 46.8% of index members are actually overbought, while only 16.8% are oversold. So, the index is oversold, yet half the index is overbought, which is something that does not happen frequently. For instance, in March of this year we saw levels reach the same territory, but overbought stocks were marginal and oversold stocks were much greater. Based on what the markets did in October, AI and tech stocks got punished the most, and the drops in many of the names were so substantial that prices moved below the 50-day moving average (oversold territory). However, a great number of these names are the largest members of the S&P 500, which is exactly why we see the index being oversold. A clear rotation out of risk-on assets and uncertainty, and into sectors like healthcare, utilities, and staples; but also, into treasuries where risk is low and elevated yields give them a premium worth investing in.
AI’s Hidden Bill & Rising Insurance Costs
Source: Michael Cembalest, JPMorgan (Now You Can See Everything)
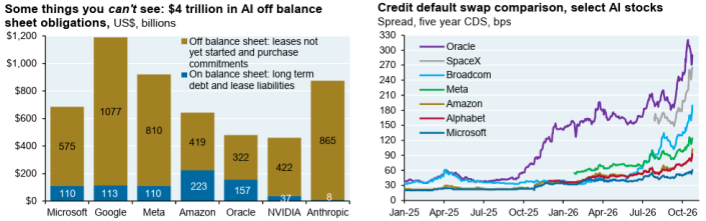
The selloff on November 5th was the kind of day more typical of a bear market than a bull market, but it is too soon to know what direction we are headed. So, we know the selloff was massive, but what are some of the more important variables that have led to the investors questioning the future of the AI buildout. Most things in life come at a cost, and for this revolutionary technology, those costs are under a microscope at all times due to the sheer amount of capital that is being thrown its way. Between the 7 companies listed, there is a combined $4T in off balance sheet obligations, which is pretty important to understand when trying to gauge their overall financial health. These commitments equal multiple years of operating cash flows for several of them, and it is all banking on that demand will not only keep at its current pace but speed up as well. These companies understand the potential of this technology, and the cost is great, but they know dipping their toes in the water to test it is not possible, they either jump into the deep end or sunbathe off to the side. It is too early to declare a real positive ROI on the hundreds of billions of dollars in capex and future commitments, and over the course of the last several months we have seen credit default swap contracts for these companies start to rise, reflecting an increasing risk of default and less investor confidence. These companies have been pushed down the same path that has led them to be more connected than ever before, so the trend of these spreads matter more than they do individually, and this relatively large widening gives me the belief that the longer we go without meaningful results, the less sand there will be in the hourglass.
DISCLOSURE
Past performance is no assurance of future results. Trademark Financial Management, LLC (“Trademark”) is a registered investment adviser with its principal place of business in the State of Minnesota. Trademark and its representatives are in compliance with registration requirements imposed upon investment advisers by those states in which Trademark operates. Trademark may only transact business in those states in which it is registered or qualifies for an exemption or exclusion from registration. This newsletter is limited to the dissemination of general information pertaining to its investment advisory/management services. Any subsequent, direct communication by Trademark with a prospective client shall be conducted by a representative that is either registered or qualifies for an exemption or exclusion from registration in the state where the prospective client resides. A complete list of all recommendations will be provided if requested for the preceding period of not less than one year. It should not be assumed that recommendations made in the future will be profitable or will equal the performance of the securities in this list. Opinions expressed are those of Trademark Financial Management and are subject to change, not guaranteed and should not be considered recommendations to buy or sell any security. For information pertaining to the registration status of Trademark please contact Trademark at (952) 358-3395 or refer to the Investment Adviser Public Disclosure web site (www.adviserinfo.sec.gov). For additional information about Trademark, including fees and services, send for our disclosure statement as set forth on Form ADV from us using the contact information herein or by calling 952-358-3395. Please read the disclosure statement carefully before you invest or send money. Any reference to a chart, graph, formula, or software as a source of analysis used by Trademark Financial Management staff is one of many factors used to make investment decisions for your portfolio. No one graph, chart, formula, or software can in and of itself be used to determine which securities to buy or sell, when to buy or sell them, or assist any person in making decisions as to which securities to buy or sell or when to buy or sell them. Any chart, graph, formula, or software used is limited by the data entered and the created parameters. The data was obtained from third parties deemed by the adviser to be reliable. Nonetheless, the adviser has not verified the results and cannot be assured of their accuracy.